Fall brings an important annual activity for Medicare beneficiaries: reviewing Medicare coverage for the year ahead. Read on for useful tips and contact a free local service with any questions.
Medicare Open Enrollment runs Oct. 15 through Dec. 7, giving beneficiaries — and their adult children who help them navigate health care decisions — an opportunity to review coverage and make changes for the following year. In most cases, if your current plan is still offered and you make no changes, coverage will continue into the new year. But costs, benefits, prescription coverage and provider networks can change.
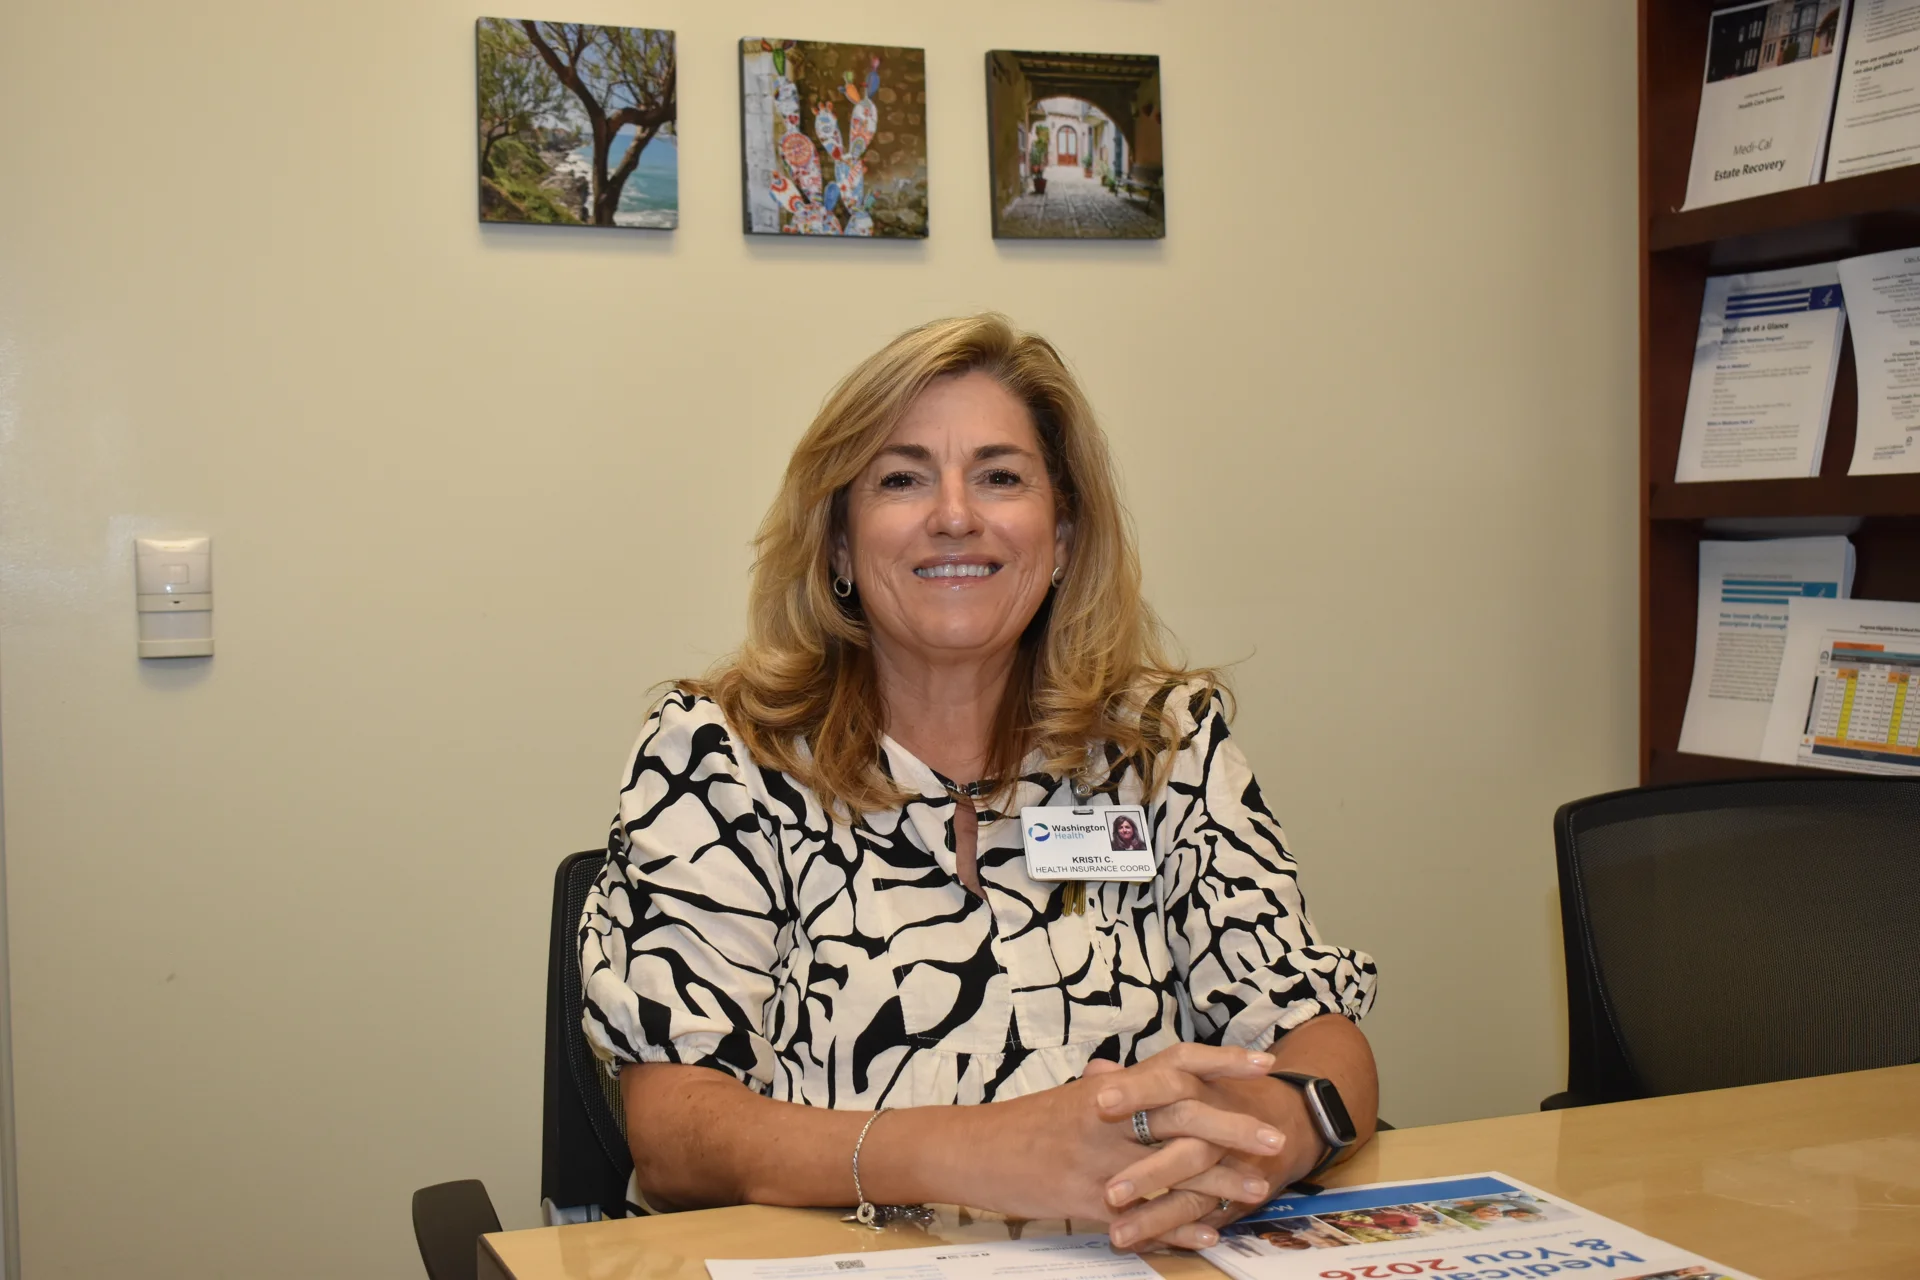
Kristi Caracappa, Health Insurance Information coordinator at Washington Health, shares wise advice to streamline the process. “Even if you’re happy with your current plan, it’s important to review, compare and ask questions. Premiums, deductibles, prescription coverage, provider networks, and other benefits can change from one year to the next. Don’t assume that since your doctor accepts your plan now and your prescriptions were all covered this year, that this will still be the case next year.”
Read the Annual Notice of Change
If you have Medicare Advantage or a Medicare Part D prescription drug plan, look for a document called the Annual Notice of Change, usually sent in September. It explains changes in your plan’s coverage and costs that will take effect Jan. 1. Review changes to premiums, deductibles, co-payments, prescription drug coverage, provider networks and other benefits. Compare what you paid this year with what you could pay next year, not just the monthly premium.
Check Doctor and Prescription Coverage
If you have Medicare Advantage, check the plan’s current provider directory or contact the plan directly to confirm your primary care physician, specialists, preferred hospital and other providers will remain in network. This is especially important if you see several specialists or receive care at a particular hospital or health system. Caracappa recommends asking these questions when confirming your coverage for next year:
- Is my doctor still in the network?
- Is my preferred hospital covered?
- Will my specialists remain in network?
- Have my Co-pays or coinsurance changed?
- Do I need referrals or prior authorization for services I regularly receive?
Make a list of medications you take, especially expensive prescriptions, and check each one against next year’s drug coverage. Caracappa recommends using Medicare.gov to check:
- Whether the drug remains on the plan’s formulary.
- Which tier it occupies.
- Your Co-pay or coinsurance.
- Whether there are quantity limits.
- Whether prior authorization or step therapy is required.
- Which pharmacies are preferred.
A plan that looks inexpensive based on its monthly premium could actually cost more if your medications move to a higher tier or your preferred pharmacy changes. Medicare’s plan-comparison tools allow beneficiaries to enter their medications to estimate drug costs.
Understand Your Choices
“One of the biggest decisions is whether to remain with Original Medicare or choose Medicare Advantage,” says Caracappa. “There isn’t one universal ‘best’ choice. The right option depends on your doctors, medications, health needs, finances, and willingness to deal with networks and coverage rules.”
Original Medicare consists of Part A, which covers hospital care, and Part B, which covers doctors and outpatient services. Those with Original Medicare can generally see any doctor or hospital that accepts Medicare. Some beneficiaries also buy a Medigap policy to help pay certain costs that Original Medicare doesn’t cover. A separate Part D plan can provide prescription drug coverage.
If you are considering leaving Medicare Advantage for Original Medicare and expect to buy a Medigap policy, check your eligibility before making the switch; the right to buy a Medigap policy is not guaranteed in every situation.
Medicare Advantage, also known as Part C, is offered by private insurance companies approved by Medicare. These plans provide Medicare-covered Part A and Part B services, and most include prescription drug coverage. Many of these plans offer additional benefits, but they typically use provider networks and may have different rules regarding referrals, prior authorization and where you receive care.
New to Medicare? Know Your Enrollment Window
“If you’re approaching 65 and enrolling in Medicare for the first time, don’t assume this Open Enrollment Period is your deadline,” points out Caracappa. For most people, turning 65 triggers a seven-month Initial Enrollment Period that begins three months before the month you turn 65, includes your birthday month and ends three months afterward.
People with group health coverage based on current employment should check with their benefits administrator and Medicare about timing; rules can vary based on the type of coverage and employer size.
Free Local Help Is Available
Washington Health’s Health Insurance Information Service is celebrating its 30th anniversary, and Caracappa has led the service for 17 years. The free, confidential service offers phone support and personal consultations to community members, regardless of where they receive their health care.
For free, confidential help with health insurance questions, visit washingtonhealth.com/healthinsurance, email healthinsurance@washingtonhealth.com or call 510.818.7005 from 8 a.m. to 5 p.m. Monday through Friday.